
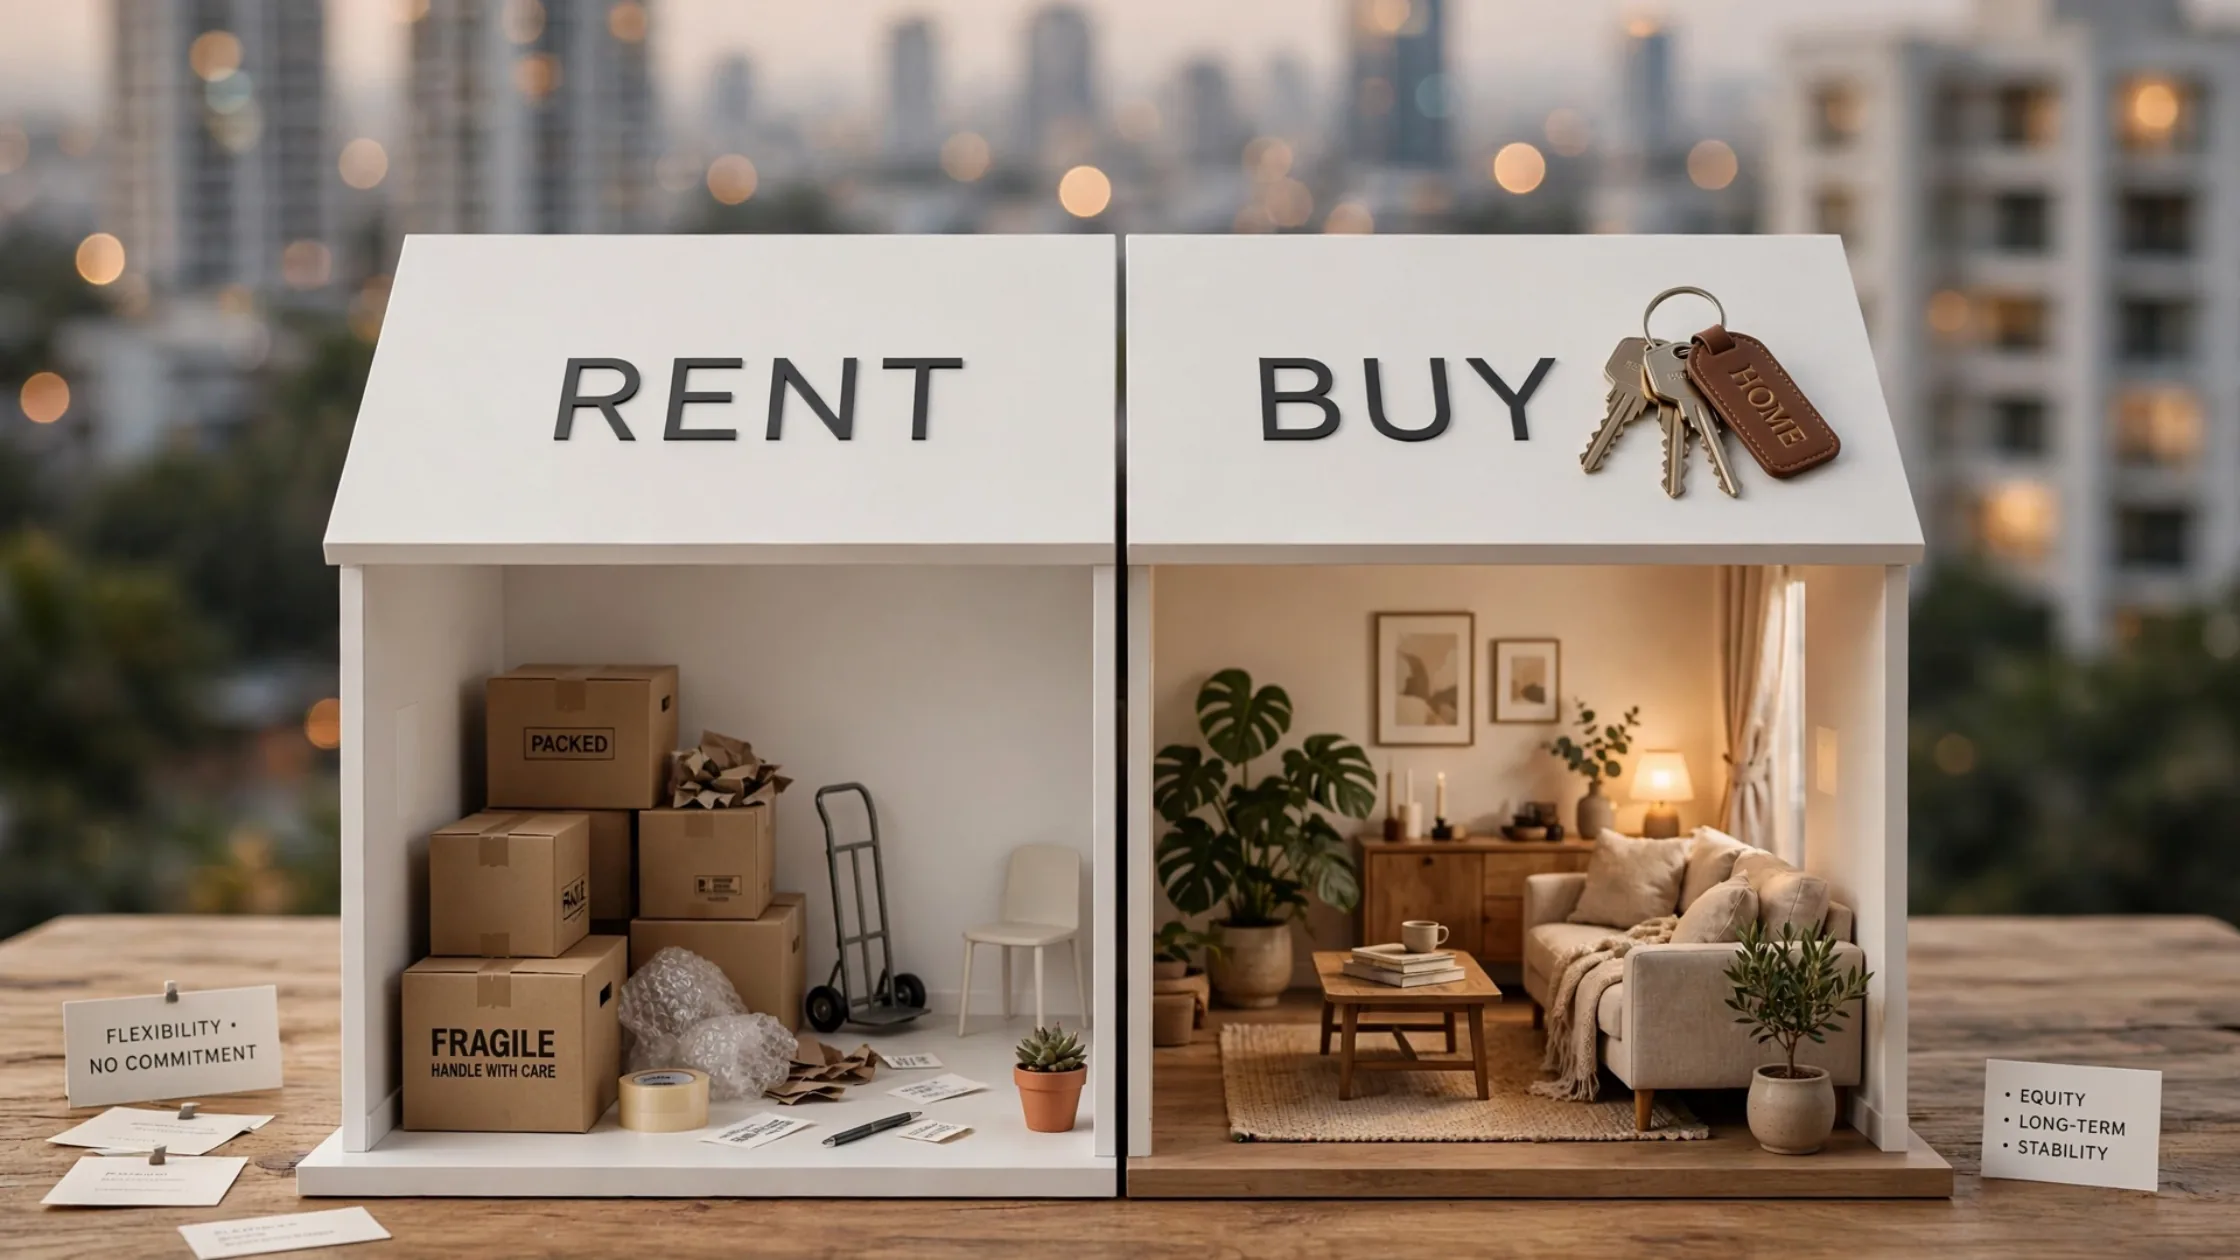
Your landlord just asked for another hike, and the flat you liked off Sarjapur Road quotes eighteen months to possession. That’s usually the moment people start running the buy vs rent in Bangalore maths on a phone calculator at 11pm, somewhere between annoyance and panic. The answer is rarely clean. Naverah Assets understands that these decisions need more than a quick comparison of EMI and rent.
Bangalore behaves differently from most Indian metros. Rents move quickly, resale stock is deep, and the city keeps stretching along metro and highway corridors. So buy vs rent in Bangalore depends less on timing the market and more on three things you already know: how long you’ll stay, how stable your income is, and whether you can absorb a big upfront cash hit without emptying your emergency fund. With guidance from Naverah Assets, buyers can assess these factors more clearly before deciding whether renting or purchasing makes better sense.
People wait for a “correction” that rarely arrives in the shape they imagine. What shifts the equation is your holding period. Sell inside three years and transaction costs alone eat most of any paper gain. Hold eight years in a corridor with real infrastructure delivery and the story changes completely.
There’s a rough rule worth applying honestly. If you can’t picture yourself in the same city for five to seven years, renting usually wins on pure numbers. Job mobility in the tech sector is high, and plenty of people who bought near one campus ended up commuting across the city a year later. Renting keeps that flexibility cheap. Buying makes it expensive.
Renting a home in Bangalore looks cheaper monthly, and it often is. The costs that catch people out don’t show up in the rent figure.
• Security deposit: still six to ten months of rent in many independent-house and older-apartment segments, though gated projects increasingly settle at three to five.
• Annual escalation: most agreements build in a yearly increase in the mid-single digits, and landlords in high-demand pockets push harder.
• Brokerage: usually around a month’s rent each time you move.
• Moving friction: packers, deposit gaps between two homes, new fittings. Shifting every two years quietly costs a lot.
Renting a home in Bangalore means no equity build-up, but no maintenance liability either. When the lift motor fails or the terrace leaks, that’s not your bank balance. Anyone assessing buy vs rent in Bangalore should price that transfer of risk honestly rather than dismissing it.
Buying a home in Bangalore carries transaction costs that first-time buyers underestimate badly. Stamp duty in Karnataka is slab-based, with registration charges and cess on top. Add legal fees, khata transfer, and the builder’s corpus fund, maintenance advance and infrastructure deposits. Together these add a meaningful percentage to the headline price, and they’re why short-term ownership so rarely wins this argument.
Then there’s the diligence you can’t skip: RERA Karnataka registration for under-construction projects, an encumbrance certificate covering at least thirteen years, the mother deed and full title chain, plan sanction from BBMP, BDA or BMRDA, and whether the property carries Khata A or Khata B. Khata B is cheaper for a reason.
Lenders typically fund 75–90% of the agreement value depending on ticket size, so you arrange the balance plus all transaction costs from your own funds. A small change in interest rate moves your EMI noticeably over a twenty-year tenure. Run the numbers at a rate one to two percentage points above today’s, because floating rates do exactly that.
Gross rental yields across most Bangalore micro-markets sit in a modest single-digit range, and net yields land lower once you subtract maintenance, property tax, vacancy and repairs. Your EMI on the same property is almost always higher than the rent it commands. That gap is the real cost of ownership in the early years.
| Factor | Renting | Buying |
|---|---|---|
| Upfront cash | Deposit plus brokerage | Down payment, stamp duty, registration, charges |
| Monthly outgo | Rent, usually lower than EMI | EMI plus maintenance and property tax |
| Annual increase | Escalation built into agreement | EMI stable unless rates move |
| Flexibility | High, exit in a month | Low, exit costs are significant |
| Wealth effect | None, but capital stays liquid | Equity builds slowly, then faster |
| Repair liability | Landlord’s | Yours |
Ownership only wins once the rent you’re avoiding, principal repayment and appreciation together outweigh interest and transaction drag. In most Bangalore cases that crossover lands in years five to eight.
If you’re two or three years into work and your role could relocate you, renting near your office beats a long loan in a distant suburb. Commute time here is a real quality-of-life cost, and a 90-minute one-way crawl on ORR is a heavier tax than most people budget for.
Once schooling, extended family and a stable job anchor you, the rent vs buy in Bangalore calculation swings towards ownership. You get pricing certainty against a rental market that keeps climbing, and you stop rearranging your life around someone else’s sale plans.
Treat Bangalore property investment as a decision distinct from buying a home to live in. Yield alone rarely justifies it. A specific thesis does: an under-served pocket near a confirmed metro extension, a plot in a BMRDA-approved layout with clean title, or a well-priced resale where employment is growing. Bangalore property investment built on brochure promises disappoints.
Whitefield, Sarjapur, Hebbal, North Bangalore towards Devanahalli and the ORR belt all behave differently. North Bangalore rides airport-driven demand and infrastructure spend; the eastern corridors trade on employment density. Rents in established employment pockets run high relative to purchase prices, which nudges the rent vs buy in Bangalore answer towards buying if you’re staying put. In peripheral areas the reverse holds, because rents stay soft while capital values already price in future infrastructure.
Check delivery, not announcements. A metro line under construction versus one merely sanctioned changes when home buying in Bangalore in that pocket actually pays off.
Work through this list before you sign anything.
1. Write down your honest holding horizon, then subtract two years for realism.
2. Total the upfront cash for buying against your liquid savings.
3. Stress-test the EMI at a higher rate and at three months without income.
4. Verify RERA Karnataka registration, encumbrance certificate, khata status and approval authority before any advance.
5. Compare the rent of an equivalent flat in the same project against your projected EMI.
Anyone approaching home buying in Bangalore for the first time should get an independent legal opinion, not just the seller’s paperwork.
Month to month, renting is almost always cheaper because rental yields sit well below home loan rates. Buying wins over longer horizons once principal repayment and appreciation compound. For most buyers weighing buy vs rent in Bangalore, the break-even lands somewhere between the fifth and eighth year of ownership.
Five years is the realistic minimum and seven is safer. Stamp duty, registration, brokerage and loan processing costs are sunk the day you transact. In the buy vs rent in Bangalore maths, selling earlier usually means those costs cancel out any appreciation, leaving you worse off than if you had simply rented.
It can. Many lenders are more conservative with Khata B properties and may reduce the sanctioned amount or decline outright. Khata A properties, with clear BBMP or BDA records, are treated more comfortably. Confirm khata status and lender policy before paying any booking amount or advance.
Under-construction carries delivery risk, which RERA Karnataka reduces but doesn’t eliminate. Resale gives you a finished product you can inspect and rent immediately. Under-construction usually prices lower and offers staggered payments. Match the choice to your risk appetite and how soon you need possession.
There’s no universally correct answer to buy vs rent in Bangalore—only one that fits your horizon, income stability, and appetite for paperwork. Rent while your life is still moving. Buy when it settles, and choose a location where infrastructure is actually being built rather than merely announced. Run your own numbers for both paths, including the costs nobody advertises, and revisit the decision yearly instead of treating it as permanent.
Naverah Assets can help you understand the local property market and explore options based on your needs. If you’re weighing up your choices, speaking with an experienced local property team like Naverah Assets, along with an independent legal advisor, is a practical way to get answers matched to your situation. Follow Naverah Assets on Instagram for more property insights.


